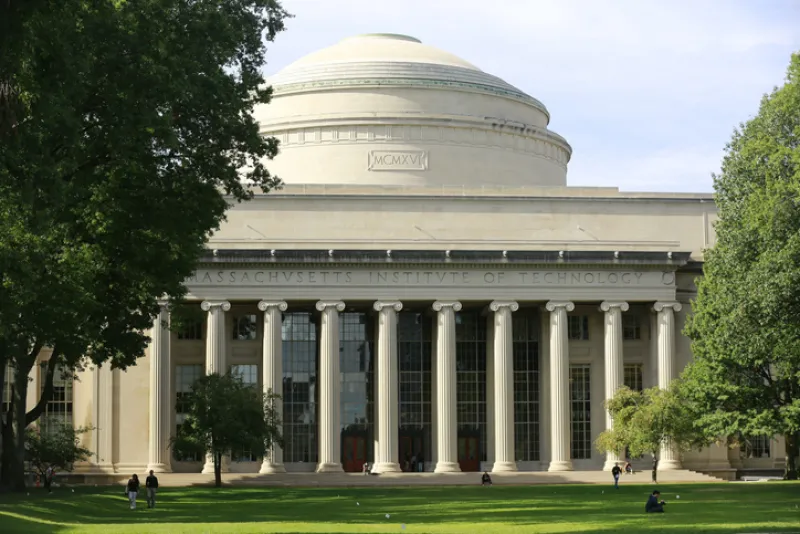
While large elite universities so far continue to report double-digit fiscal year endowment returns, the gap between the top and bottom performers is huge.
Stanford University’s $61.5 billion pool returned a net 31.7 percent for its latest fiscal year and the University of Pennsylvania’s $31.1 billion endowment posted a 27.4 percent return. Meanwhile, the Massachusetts Institute of Technology reported a 10.3 percent return for its $29.2 billion endowment.
“M.I.T.’s recent performance is a powerful reminder of just how wide the dispersion among large endowments can be,” said Brad Alford, founder of Alpha Capital Management. “Even institutions with extraordinary resources, access and investment teams can experience periods of significant underperformance.”
Stanford Management Co.’s CEO Robert Wallace attributed the elite California university’s annual results to “strong performance from our public and private equity positions, along with a very healthy contribution from our absolute return strategies.” Neither Penn nor M.I.T. provided further information on the returns of more asset classes; M.I.T. declined to comment beyond what was in its press release and treasurer’s report.
Long term, the performance gap narrows. For the 10-year period ending June 30, MIT posted an annualized return of 11.7 percent, compared with 12 percent for Penn and 12.5 percent for Stanford.
Some large universities have generated gains in the high ‘30s. The University of North Carolina and Washington University in St. Louis saw returns of 37.8 percent and 37.3 percent, respectively, thanks in part to early investments in SpaceX.
Last year, Markov Processes International estimated that digital assets drove M.I.T.’s strong return of 14.8 percent for FY25. New research from MPI suggests that this exposure to crypto may have now become a drag on performance.
MPI’s model attributes roughly half of Penn’s and Stanford’s returns to incremental SpaceX exposure. Analysis suggests that M.I.T.'s excess economic exposure to SpaceX reached approximately 2.2 percent in FY25. MPI stressed that the figure is an estimate rather than a disclosed holding.
While annual returns cannot establish whether M.I.T. reduced or sold its SpaceX shares, M.I.T.’s SpaceX signal disappears in MPI’s updated model, while its exposure to digital assets remains.
“That makes crypto a plausible contributor to M.I.T.’s weaker result,” MPI’s founder and CEO Michael Markov hypothesized. While the presence of crypto offers a possible explanation for part of M.I.T.’s results, Markov caveated that it doesn’t explain the full gap.
M.I.T.’s weaker relative performance comes as the Cambridge-based research university faces increased budget and funding pressures, including an increased federal tax on endowment investment income, with the top rate rising from 1.4 percent to 8 percent. President Sally Kornbluth wrote in her welcoming letter to students last month that “the world outside of MIT is still very complicated for us,” citing threats to visas, cuts to federal funding, and the new tax burden, before adding: “no one can predict what’s coming at us next.”