Hedge funds, even some of the most storied names, were hard hit last month as investors wrestled with skepticism of AI companies, speculation about the mid-term elections in the U.S., and continued spikes in oil prices.
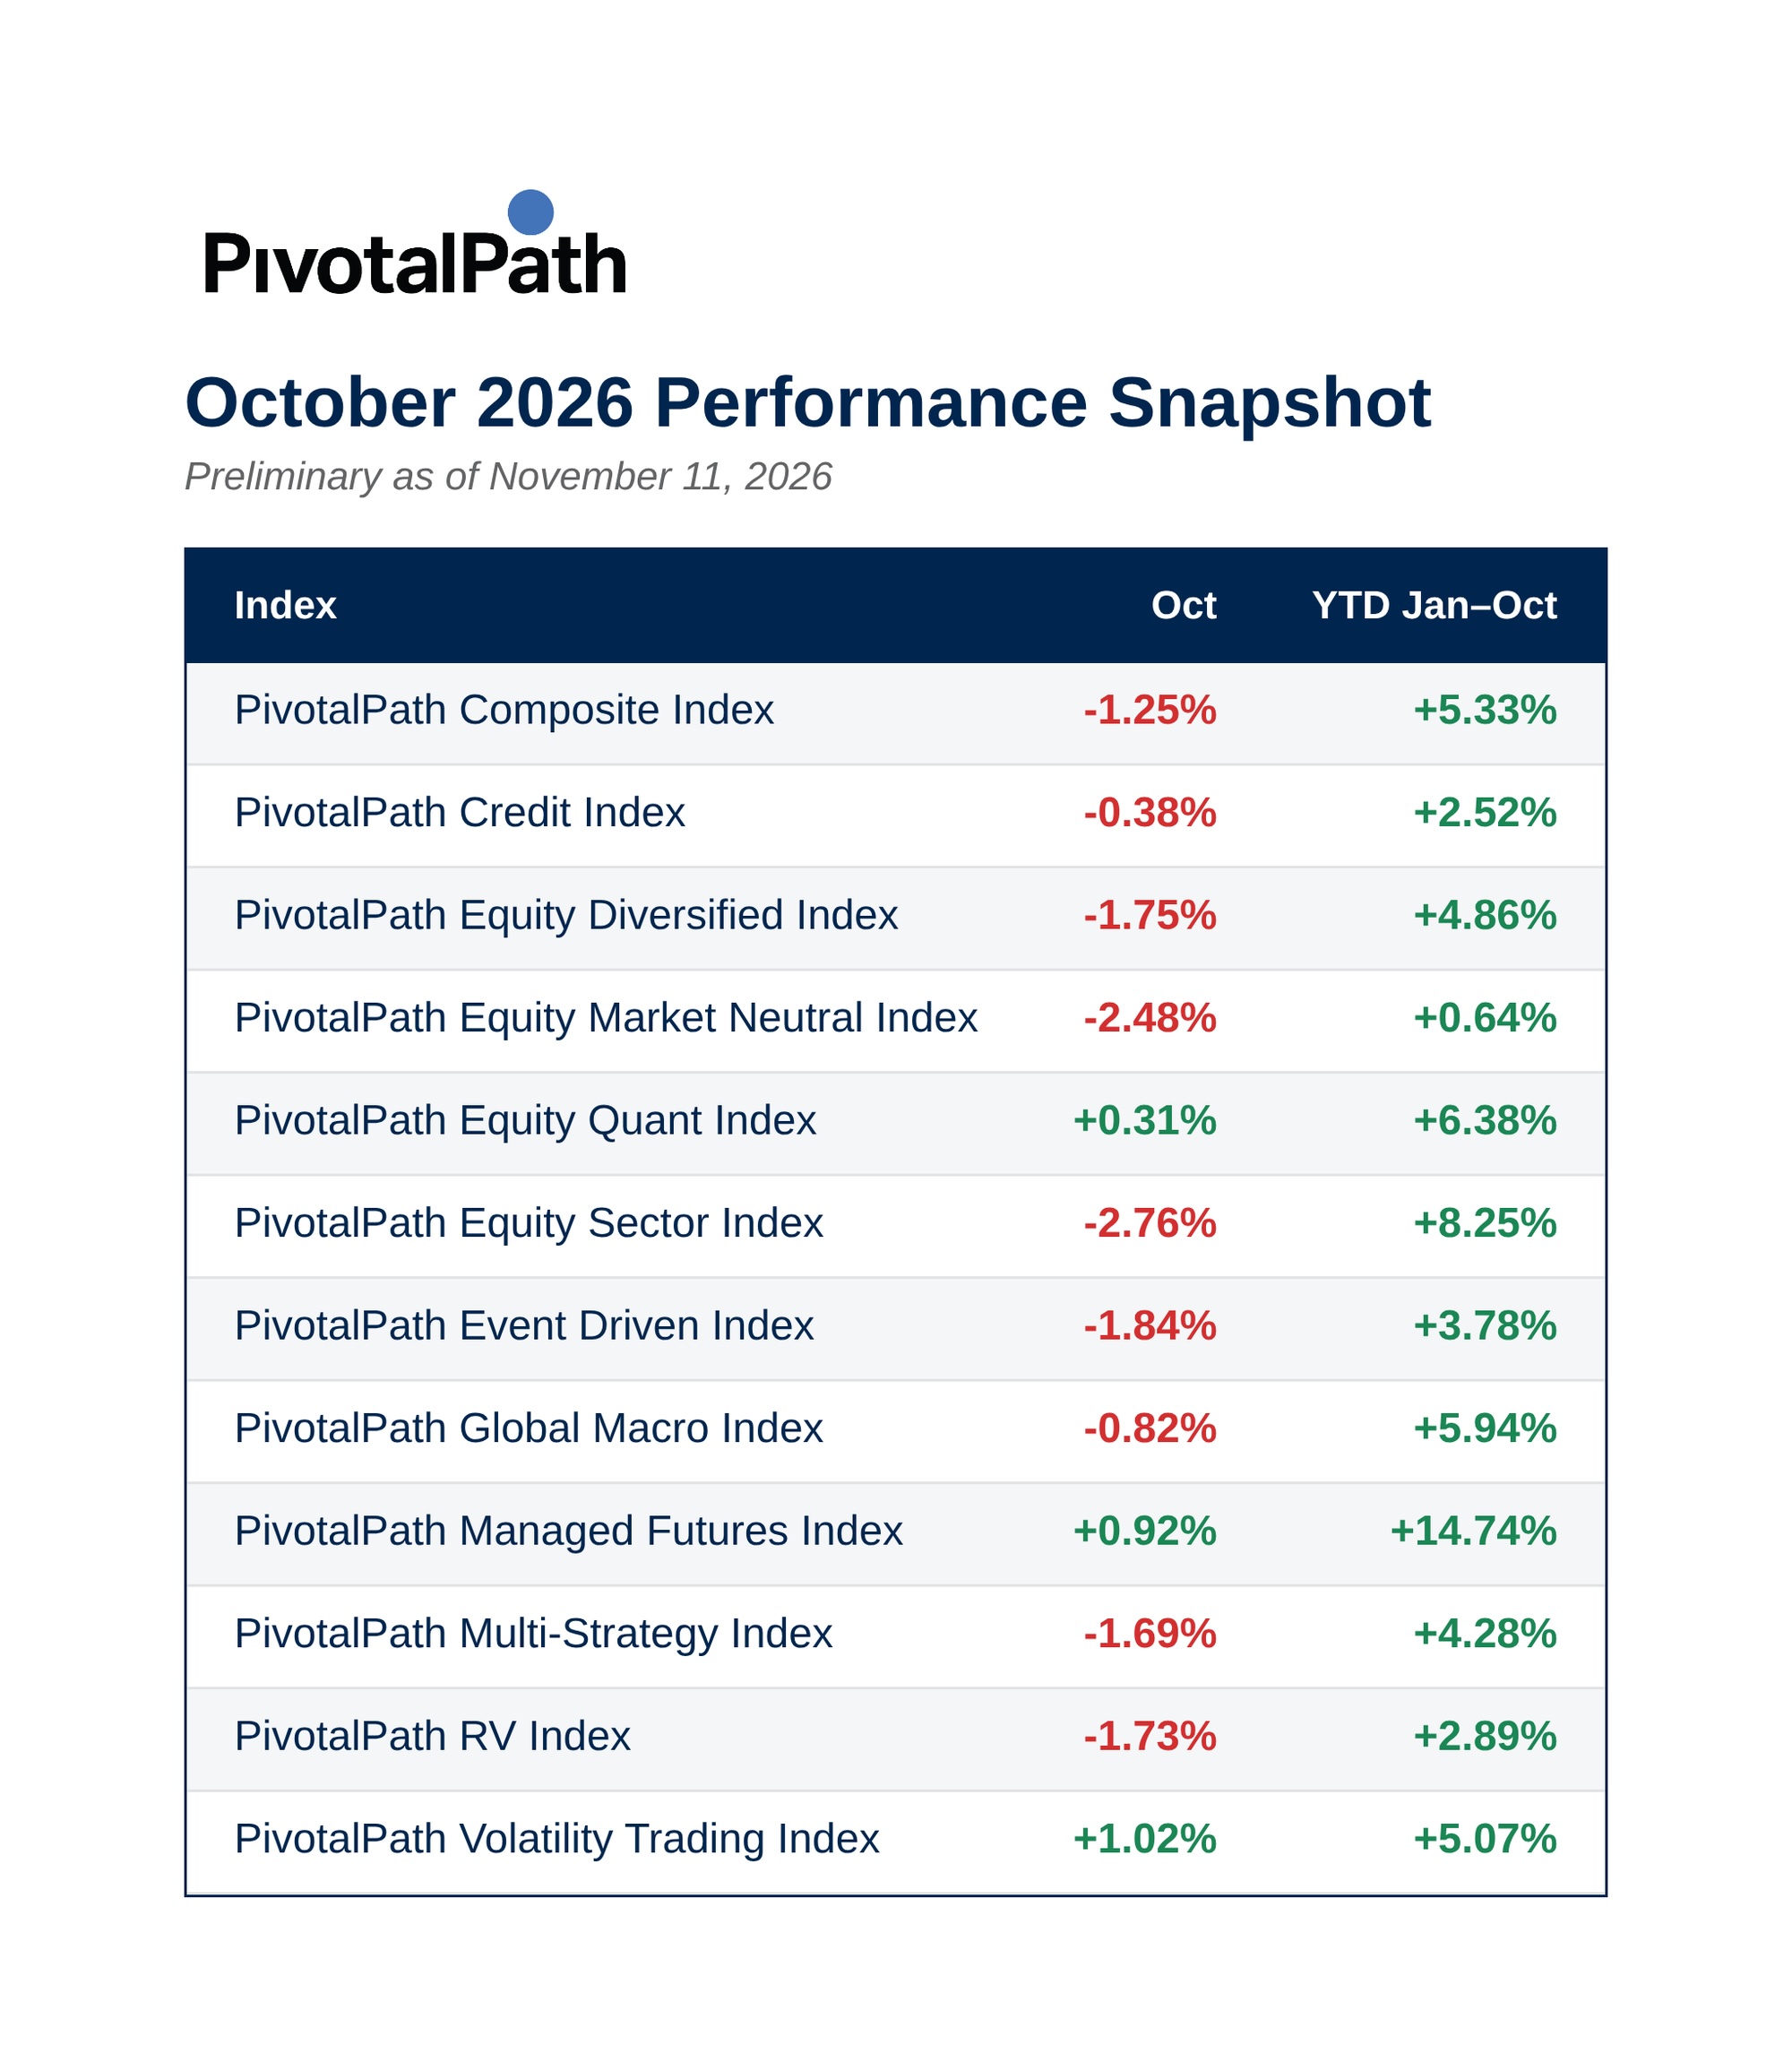
Take a look at the results. The PivotalPath Composite Index lost 1.25 percent in October, more than the S&P 500’s loss of .87 percent, according to the hedge fund research firm’s latest data. The Equity Market Neutral Index, a strategy whose performance aims to be independent of the market, lost 2.48 percent — the worst October for the index on record.
Every month Institutional Investor publishes a subset of hedge fund indices from PivotalPath. Scroll to the end of the article to view 12 indices, including credit, equity diversified, equity market neutral, global macro, relative value, and others.
While the data is still preliminary as of November 11, the performance of Relative Value (- 1.73 percent), Multi-Strategy (- 1.69 percent), Equity Market Neutral (- 2.48 percent), Event-Driven (- 1.84 percent), Equity Diversified (- 1.75 percent), and Equity Sector (-2.76 percent) was among the weakest 10 percent of all monthly returns in the last ten years.
But the losses may not be surprising to investors and analysts watching, among other things, how correlations between hedge fund strategies and the S&P 500 have been rising. Those correlations are a signal that during a market downturn, some hedge fund strategies that investors are expecting to protect them may fall in tandem with the broader market.
Blame it, of course, on AI. While investors have been worried about concentration in the market and major benchmarks for years, AI has deepened the problem. As Institutional Investor reported in May of this year, technology funds had their best month in 26 years. Something to celebrate. But digging deeper, that performance essentially matched what the S&P delivered. In fact, that’s the closest match ever. In May, six of PivotalPath’s indices were also at record high correlations with global benchmarks as well.
(Click here for the latest index performance data and access to PivotalPath's full suite of hedge fund indices.)
Back to October. Fundamental and systematic equity books suffered losses as crowded AI positions unwound, the momentum trade reversed, and managers cut risk as they faced the downturn.
The S&P 500’s small decline masked bigger declines in slices of the market. PivotalPath’s FAANG factor index was down 9 percent, SAAS was down 5 percent, and the Mag 7 declined 4.7 percent.
Last month, investors’ own performance came down to manager selection in many strategies. The difference between top and bottom managers was particularly wide in a number of strategies. In Equity Diversified the differential was 6.23 percent, in Credit it was 2.10 percent, in Multi-Strategy it was 3 percent, in Relative Value it was 2.93 percent, and in Equity Market Neutral it was 3.66 percent.